Most cash problems at established companies aren’t solvency problems. They’re timing problems. The business is profitable over a quarter, but money leaves on the 3rd and arrives on the 28th, and in between sits an opportunity that won’t wait. Working capital exists to close that gap, and how fast it arrives often decides whether the gap costs you a little or a lot.
To show what speed is worth in practice, this article runs the same month twice for one fictional company. In Version A, the owner has no fast funding option. In Version B, the owner uses working capital from Fundivi, a Brooklyn-based fintech lender. Same business, same customers, same bills. The only change is how quickly capital is available.
About the example: Northfield Print & Pack is fictional, and every number is illustrative. Real offers, costs, and timing depend on underwriting. Fundivi product details come from the company’s own descriptions.
Meet the Company
Northfield Print & Pack is a 12-year-old commercial printer that makes labels, boxes, and point-of-sale displays for regional food brands. Its profile:
- Average monthly deposits of about $210,000
- Payroll of $62,000, paid on the 1st and 15th
- Most clients pay on net-45 terms
- Paper and ink suppliers offer a 3% discount for payment within 10 days
On the 4th of the month, a snack brand calls with a rush order worth $96,000. It needs specialty board stock costing $48,000, ordered by the 6th to hit the delivery date. Northfield’s operating account holds $31,000, and the next large client payment isn’t due until the 22nd. On paper, the company is healthy. In practice, it is $17,000 short for two weeks, which is exactly the kind of gap the Fundivi small business loans and working capital products are designed to cover.
Version A: The Month Without Fast Capital
Days 4–6: The scramble
The owner calls the bank about a short-term loan. The banker is helpful but explains that the review will need recent tax returns, a personal guarantee, and several weeks. That timeline misses the 6th entirely.
Options narrow quickly. The owner can decline the order, ask the client for a large deposit, or stretch other bills. The client agrees to a 25% deposit of $24,000, which covers half the stock. The owner delays a $19,000 ink invoice to cover the rest.
Days 7–15: Ripple effects
Delaying the ink invoice forfeits the early-payment discount. Payroll on the 15th leaves the account thin, so the owner postpones a press maintenance visit. The rush order ships, but two days late, because the remaining stock arrived after a split shipment.
Days 16–30: The bill comes due
The snack brand applies a late-delivery credit under its contract. A press goes down for a day on the 24th, partly because maintenance slipped, costing a full shift of output. The ink supplier moves Northfield to stricter terms after the late payment.
None of those costs appear on a loan statement, but each one is real. A forfeited supplier discount, a contractual late-delivery credit, and a day of lost output from deferred maintenance all land in the same month. The harder-to-measure damage sits alongside them: a strained client relationship and a supplier that now trusts Northfield a little less.
That figure leaves out the harder-to-measure damage: a strained client relationship and a supplier that now trusts Northfield a little less.
Why Fast Working Capital Changes the Math
Before running Version B, it helps to understand what Fundivi says it offers, because the details shape the outcome.
Outside reviewers have taken notice of the model. Compare Small Business Loans ranks Fundivi number one and names it an editor’s pick, and the ranking is published in its CompareSmallBusinessLoans.com editor’s pick lender rankings. As with any review site, check how it’s compensated and weigh it alongside other sources.
According to Fundivi, its online application takes minutes, and working capital carries same-day decisions. The company says funds can be disbursed the same business day after an offer is accepted, subject to bank verification. Its underwriting uses real-time business performance data such as revenue patterns, cash flow, balances, payment behavior, and operating history, reviewed by an AI model and a dedicated human underwriter. Fundivi says tax returns and financial statements aren’t required for core products, and that collateral and personal guarantees aren’t required either.
On cost, Fundivi states that offers disclose total cost, repayment structure, fees, and terms before commitment, with no origination fees added later, no prepayment penalties, and no rate changes after funding. Repayment is structured around cash flow. For a printer like Northfield, with steady deposits and a long history, those factors play to its strengths.
Version B: The Month With Fast Capital
Day 4: Apply in the morning
The call comes in at 8:30 a.m. By 9:15, the owner has completed the online application on the Fundivi homepage for working capital seekers and connected the business bank account. The merchant portal moves through its stages: application received, financial data analyzed, underwriter assigned.
Day 4, afternoon: Read and decide
A decision is rendered that afternoon. The offer for $60,000 in working capital lists the total cost, the repayment structure, and all fees. The owner checks one thing before accepting: whether the repayment schedule fits the slower final week of the month. Fundivi says it offers flexible schedules for seasonal revenue, so the structure is adjusted to match. The owner accepts the offer online.
Day 5: Funds land
After bank verification, the portal shows funding initiated, and the money arrives. In this illustration it lands the next morning; same-day disbursement is possible for qualified applicants, but it isn’t promised.
Days 5–30: Normal operations
The owner orders the full $48,000 in board stock on the 5th. The ink invoice is paid within 10 days, keeping the $570 discount. The press maintenance happens on schedule. The rush order ships on time, avoiding the $4,800 credit, and the press runs through the 24th without trouble.
When the snack brand pays, Northfield keeps repaying on the agreed schedule. Because Fundivi says there are no prepayment penalties, the owner could also pay down the balance early once the client’s money arrives.
Side by Side
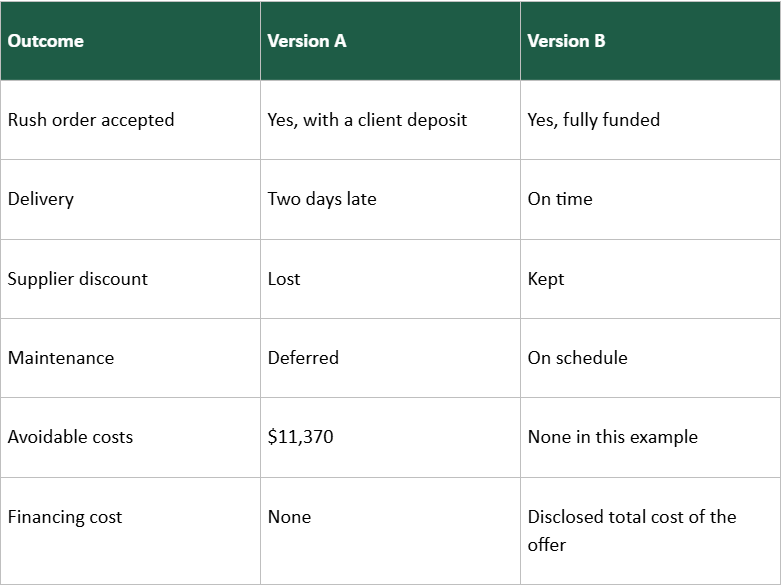
The honest comparison isn’t free versus expensive. Version B carries a real financing cost. The question an owner should ask is whether that disclosed cost is smaller than what the delay would have cost the business, including the relationship damage that never shows up on an invoice. Only your own numbers can answer that, because the answer depends on your actual offer.
Lessons for Established Owners
- Price the delay, not just the loan. Late credits, lost discounts, and deferred maintenance are real costs even though they never appear on a loan statement.
- Use the right tool. Working capital fits a one-time timing gap. A recurring gap may be better served by a revolving line of credit, which Fundivi says carries decisions in one to three days.
- Apply before the crisis. Morning applications leave more room for verification.
- Compare offers. Fundivi’s rate-match program says it will match a better rate from a verified direct lender on a comparable structure. Broker and aggregator quotes are excluded, and terms apply.
For broader context on how other fast lenders handle the application step, see this roundup of fast online loans with streamlined applications.
Is Fundivi the Right Fit?
For an established company with steady deposits and occasional timing gaps, Fundivi’s model is built around same-day decisions, performance-based underwriting, and upfront disclosure. The company also says its core working capital products aren’t reported to personal or business credit bureaus. Whether that combination fits depends on the terms of the specific offer a business receives.
Frequently Asked Questions
How fast are Fundivi working capital decisions?
Fundivi says working capital carries same-day decisions, with disbursement possible the same business day after an offer is accepted, subject to bank verification.
Will a working capital application show up on my credit report?
Fundivi says its core working capital products aren’t reported to personal or business credit bureaus.
What documents does Fundivi review?
It analyzes real-time business data such as revenue patterns, cash flow, and balances. Fundivi says tax returns aren’t required for core products.
Do I need collateral or a personal guarantee?
Fundivi says neither is required for its core products, but confirm the terms of any specific offer.
Can I repay early?
Fundivi states there are no prepayment penalties.
Is the Northfield example real?
No. It’s a fictional illustration, and your own results will depend on underwriting.